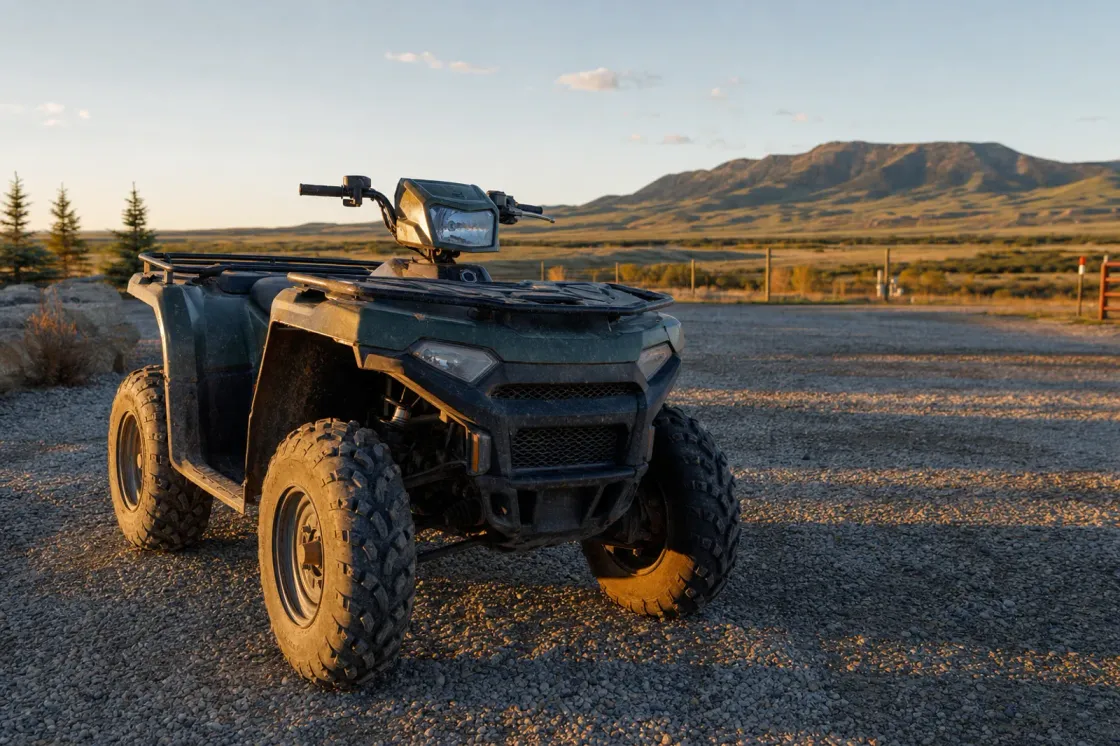
Financing an ATV is the most direct way to get onto the trail without paying the full purchase price upfront. Instead of draining your savings, a dealership finance desk sets up a predictable payment schedule tied to the exact machine you pick.
Ride Motor Company works with powersports buyers across Alberta and all of Canada, with physical dealership locations and service centers in Edmonton and Leduc. Knowing how the desk structures your file turns the financing process into a clear, stress-free step toward your next quad.
Financing an ATV starts before the desk
The smoothest financing deals happen when you take two practical steps before you ever talk numbers with a finance manager.
First, pick a specific machine from live inventory. Lenders do not write blank recreational loans without knowing the collateral. When you have a real quad in mind, the desk can match the loan request to the actual value of the unit.
Second, recognize that new and used quads follow different paths. A brand-new machine comes with clear factory pricing and straightforward approval structures. A pre-owned quad requires looking at mileage, condition, and past ownership. Deciding on your target machine category early keeps your expectations clear.
What lenders look at when you finance an ATV
When you apply to finance an ATV, lenders look at your entire personal file rather than just a single score. They review your employment history, your monthly income, and your existing debt commitments to ensure the payment fits your budget.
In Canada, lenders pull your credit bureau, which is your official credit report, to see your payment history. In Alberta, financial institutions rely on your beacon score, the Equifax credit rating used across the province, to determine the initial interest tier.
Lenders also assess the machine itself. They look at the loan-to-value, the ratio between the loan amount and the quad value, to ensure they are not over-advancing on the unit. For every machine, they check the book value, the wholesale price standard for that year and model, to establish lending limits. Any advertised rate is offered OAC, short for on approved credit, meaning final approval depends on your verified background.
The documents to bring before you apply
Having your paperwork organized in advance speeds up the financing process. When you arrive with complete documentation, the finance desk can submit your application immediately and receive faster lender decisions.
Bring valid government-issued photo identification, such as a driver licence or passport, to verify your identity. Gather proof of income, including your most recent pay stubs or your last two years of tax notices if you are self-employed. Include a void cheque or pre-authorized debit form from your bank to establish payment processing, along with a recent utility bill to verify your residential address.
If a lender needs additional clarification on your income or identity, they will issue stips, short for lender stipulations, requesting added paperwork before releasing funds. Having clean primary documents ready keeps these requests to a minimum.
What happens at the dealership desk
Once you select your ATV and provide your paperwork, the dealership finance team goes to work. The finance manager reviews your file, selects the lenders best suited to your credit profile, and submits the application through secure dealer networks.
The desk waits for underwriting feedback from the lenders. When the offers come back, the manager presents the options, outlining the interest rate, term length, and monthly or bi-weekly payment amounts.
Every approval comes back with specific conditions. The desk explains these terms clearly so you understand your total commitment before signing any binding agreements.
How the payment talk works
The payment conversation breaks down the total cost of ownership into clear, manageable numbers. Your monthly commitment is determined by three main elements: the purchase price of the ATV, the interest rate, and the loan duration.
The repayment duration is the amortization, the total period over which the loan balance is scheduled, typically ranging from 36 to 84 months for powersports units. A longer term lowers your regular payment, while a shorter term reduces the total interest paid over the life of the loan.
You can explore your options and start the payment process directly through the financing portal. For a comprehensive breakdown of payment structures and interest considerations across Alberta, review the ATV financing guide.
Using financing for a used ATV
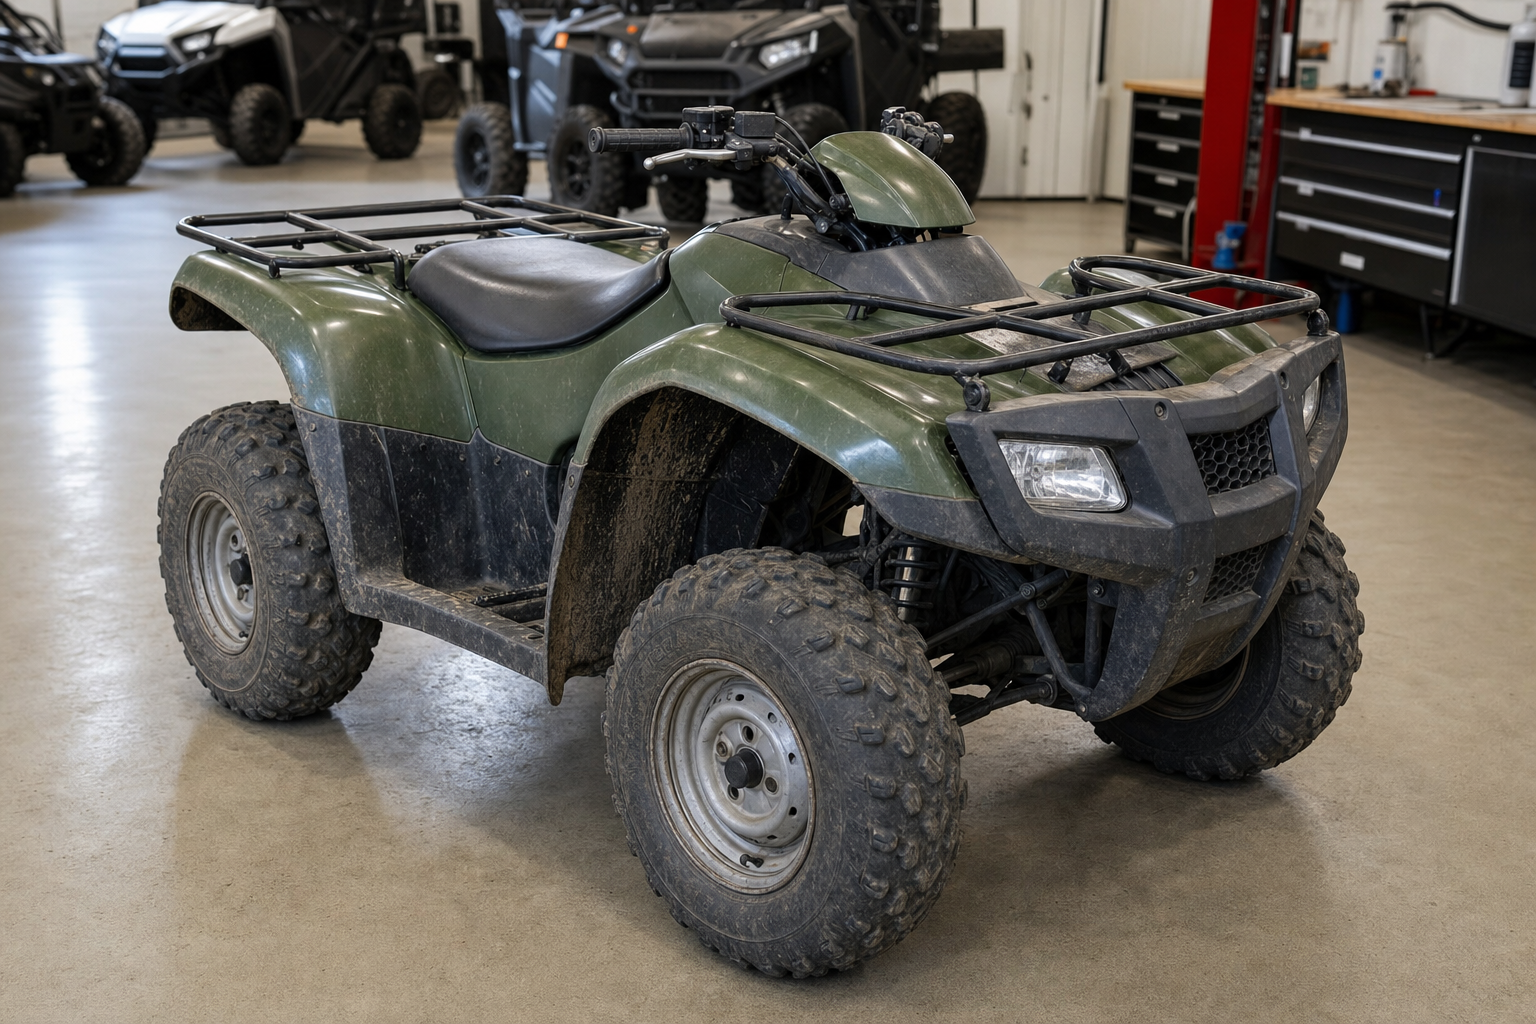
Financing a pre-owned ATV offers strong value, but lenders review used machines with extra diligence. They examine the overall mechanical condition, total running hours, and maintenance history of the quad.
When considering a used machine, verify that the unit has a clean title free of any lien, a legal financial claim held by a previous lender. Dealerships handle this title search automatically, ensuring you take ownership without inheriting prior debt.
A modest down payment on a used quad helps bridge any difference between the selling price and the lender's advance limit, giving you broader financing choices and competitive terms.
When the loan is approved
Once you accept the lender terms and satisfy any remaining documentation requirements, the financing contract is finalized. You sign the loan agreement, set up your pre-authorized payment schedule, and schedule the delivery or pickup of your ATV.
When you are ready to take the next step and secure your machine, you can start the payment process online before visiting the showroom. Handling your financing upfront lets you focus on picking the right machine and getting out on the trail.
| Document | Why the desk needs it | What to bring |
|---|---|---|
| Government photo identification | Confirms your legal identity for the loan contract | Valid Canadian driver licence or passport |
| Proof of income | Proves regular earnings to support the monthly payment | Recent pay stubs or bank statements for self-employed buyers |
| Banking information | Sets up monthly pre-authorized payments | Void cheque or direct deposit form from your bank |
| Proof of address | Confirms your current physical residence | Recent utility bill or bank statement showing your name |
| Unit details | Connects the loan amount to a specific machine | Stock number, year, make, and model from live inventory |
| Factor | New ATV | Used ATV |
|---|---|---|
| Lender valuation | Based on invoice price and manufacturer guidelines | Based on market valuation guides, age, and hours |
| Term flexibility | Longer repayment terms often available | Terms adjust based on machine age and wear |
| File preparation | Standard income and identity verification | Requires title verification and mechanical condition review |
| Down payment impact | Lowers your monthly commitment | Helps align loan totals with unit market value |
Take the next step
Put this guide to work by comparing inventory or reviewing your financing options.
Straight answers
Frequently asked questions
How does financing an ATV actually work?
A lender pays for the quad and lets you pay it back in monthly installments over a set term. The dealership finance desk collects your information, submits it to a network of lenders, and presents the actual terms approved for your file and machine.
Can I finance an ATV if my credit is rough?
Yes. Specialist lenders work with bruised credit, past credit events, or thin credit profiles. Approval depends on your whole financial picture, your income, and the unit you choose, rather than just one number.
What documents do I need to bring?
You need valid government photo identification, proof of income such as recent pay stubs, banking details for automatic payment setup, proof of physical address, and the stock number of your chosen ATV.
How does buying a used ATV change the financing process?
Used machines undergo valuation checks based on their age, hours, and physical condition. Lenders look at wholesale book value and verify title clearance to ensure no outstanding claims exist from past owners.
Is financing approval guaranteed before I apply?
No. Legitimate lenders and dealership desks review real income and credit documents before issuing an approval. Any promise of guaranteed approval before seeing your file is a red flag.
Useful links
Plan your next step
Keep reading
Related resources
financing
ATV Financing in Alberta: How the Payment Path Works
How ATV financing really works at a dealership desk in Alberta, what documents to bring, how used units affect approval, and honest credit talk.
financing
ATV Financing Alberta: Edmonton and Leduc Desk Path
Looking at ATV financing in Alberta? See how an Edmonton or Leduc desk reviews a file, what to bring, used-unit notes, and how to move to live inventory.
financing
ATV Loan Canada: What Buyers Should Sort Before They Buy
Looking at an ATV loan in Canada? See how the desk reads the file, what docs matter, and how Ride Motor Company starts a real payment check.
financing
Camper Financing in Canada: How the Loan Works
See how camper financing works in Canada. Know what lenders review on the unit, how your tow vehicle fits, and what documents to prepare before you apply.