A low credit score changes how lenders review your application. It does not mean you cannot buy a quad. For bad credit atv financing canada shoppers, specialized lenders still work with buyers who have credit challenges, collections, or past proposals. When you know what lenders look for, you can build a loan request that fits your budget.
If you want to review all powersports vehicles, our bad credit powersports financing guide covers side-by-sides, quads, and snowmobiles. Here is how bad credit ATV financing works on the showroom floor.
What bad credit means for an ATV loan
If you are comparing atv financing bad credit options, start with how lenders read your score. In Canada, credit scores range from 300 to 900. Credit bureaus calculate your beacon score, a credit score used by lenders, to track your payment history. Where your score sits on that scale shapes which lenders will review your file, but every lender sets its own rate tiers and cutoffs. Mainstream banks usually build their programs around stronger scores, while specialized lenders design programs for buyers lower on the scale.
Specialized powersports lenders take a different approach. Specialty finance companies offer subprime lending, loan programs designed for challenged credit, by looking at your income instead of old credit slip-ups. Subprime underwriters read your full file instead of just your score. They check when past issues happened, whether old bills are settled, and how you pay your accounts today.
What lenders look at besides your credit score
When a lender cannot rely on a high credit score, they check your everyday financial habits. The underwriter needs proof that you have steady money coming in to make each payment.
Lenders look at four main factors:
1. Income stability and job history
Lenders want steady income from a full-time job, seasonal trade work, or verified self-employment. Many also look for time at your current job, or steady work in the same field, plus monthly income that comfortably covers the payment along with your living costs. Each lender sets its own employment and income rules, so the finance desk matches your file to the lender that fits it.
2. Debt-to-income ratio
Lenders check your debt-to-income ratio, the share of income covering monthly debts, to make sure you have room in your budget. They add up your rent or mortgage, car payments, and credit card minimums. They compare that total against your gross income. Keeping other debts low makes it easier to get your ATV approved.
3. Down payment and equity
Putting cash down cuts the lender's risk right away. A down payment lowers the loan-to-value ratio, the loan amount compared to vehicle value, which protects the lender. Even $500 to $1,500 down shows good habits. It can turn a border-line file into an approval.
4. Residence history
Living at the same address for over a year shows stability. If you moved recently, a utility bill or rental lease proves your address and ties to the area.
The honest answer about "no credit check" ATV financing
You might see online ads promising guaranteed approvals or zero-credit-check financing. It pays to know what is really going on behind those ads.
No real powersports lender in Canada lends money without checking credit. Programs that claim to skip credit checks are usually high-rate loan brokers or rent-to-own setups. They often charge interest rates above 30 percent, install GPS trackers on the machine, or add huge fees to the paperwork.
Legitimate dealership financing always includes a credit check. Working with real lenders gives you clear rates, standard rules, and fixed monthly payments. Approval is never guaranteed, but an honest review keeps you safe from bad contracts.
Why used ATVs are the realistic subprime entry point
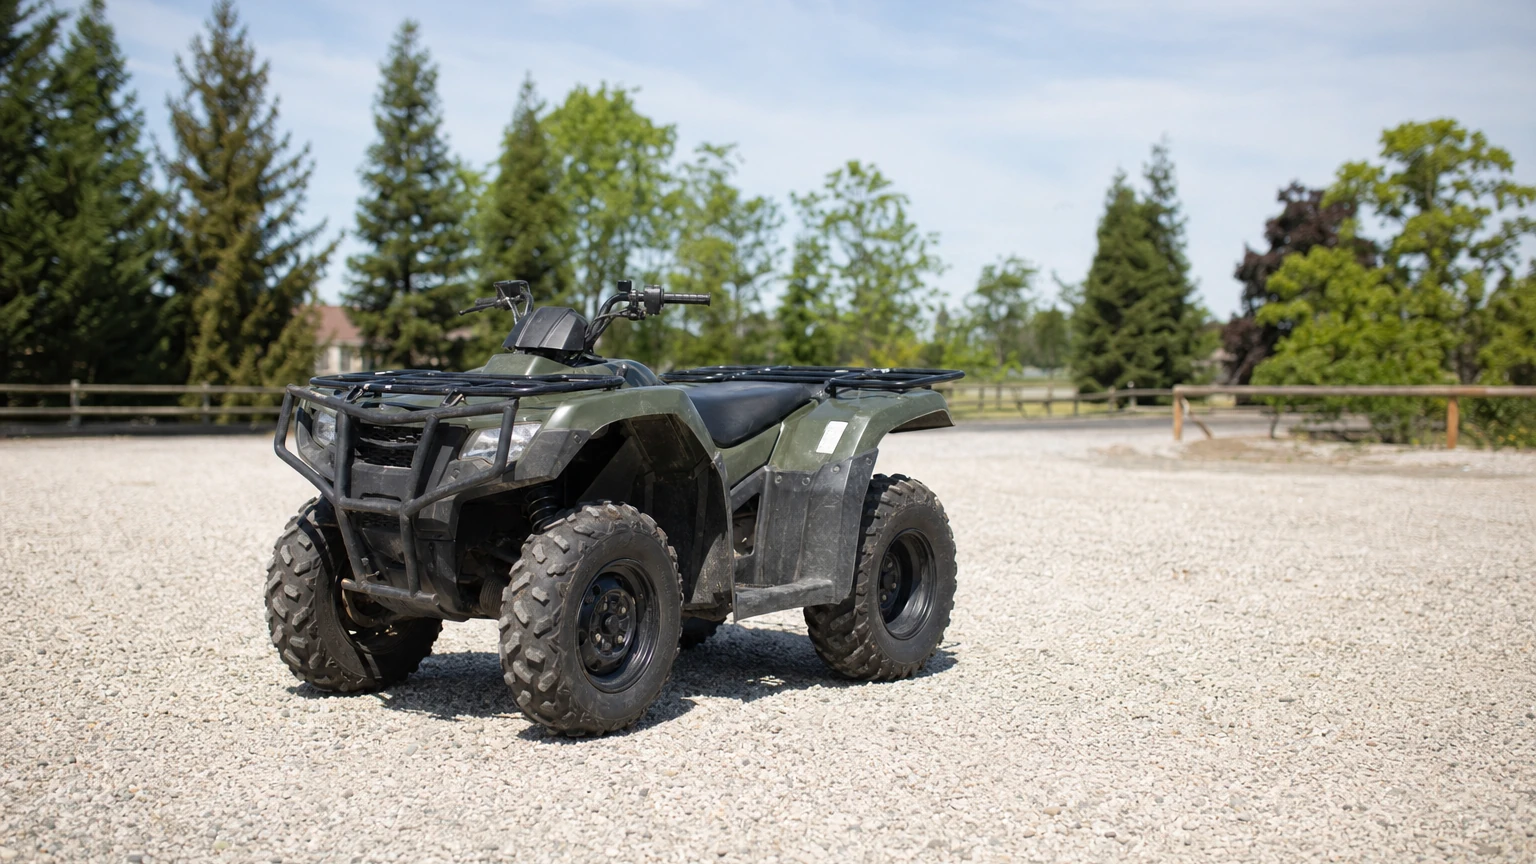
When your credit is rebuilding, the quad you pick matters a lot. New high-end ATVs often cost between $15,000 and $25,000. Asking a lender for $20,000 on a recreation toy is a tough sell.
A solid used quad priced between $6,000 and $11,000 is much easier to finance. For details on loan costs and payments, check our guide on how ATV financing works.
Used quads offer clear benefits when you need financing:
- Smaller loan balance: Borrowing $8,000 means lower payments and easier income rules than financing a $20,000 machine.
- Slower drop in value: A used quad has already taken its biggest drop in price. That keeps the value close to what you owe.
- Better odds of approval: Lenders are far more willing to approve smaller loans for buyers with past credit trouble.
Down payments: what to expect with challenged credit
A down payment is your best tool when your credit score is low. Prime buyers might get zero-down deals on new machines, but subprime lenders usually want some cash upfront.
Putting money down helps your application in three ways:
- It lowers your monthly payment by cutting the total amount you borrow.
- It can make a shorter loan term affordable, and a shorter term saves you money on interest.
- It gives the underwriter a solid reason to approve your deal.
To see common rates and terms in Canada, read our guide on getting an ATV loan in Canada.
How the application actually works
Financing an ATV with bad credit is simpler when you have your papers ready. Here is the process from start to finish:
- Send in your basic details: You fill out a short online credit form with your job details, housing costs, and contact info.
- Desk review and pre-qualification: Our finance team looks over your file. We match your budget to the right lender before sending applications.
- Document check: When a lender approves your file, they send stipulations, conditions required before releasing loan funds, like pay stubs or proof of insurance.
- Quad selection and loan setup: You pick the ATV that fits your approval. Setting a clear amortization period, the scheduled time to repay the loan, keeps your payments comfortable.
- Sign papers and take delivery: You review the contract, rate, and payment dates. You sign the papers and pick up your quad or set up delivery.
Riding toward better credit
ATV loans for bad credit get you on the trails, and they can also help you rebuild credit. Whether your lender reports your payment record to Equifax, TransUnion, or both depends on the lender, so ask before you sign.
When your lender does report, paying on time every month builds a solid record on your bureau file. That steady history is what helps lift your credit profile over time. An ATV loan does not guarantee a higher score on its own, but paying on time shows future lenders that you are back on track.
| Credit situation | Common down payment range | Common loan term range |
|---|---|---|
| Fair credit (600 to 650) | 0% to 10% cash down | 36 to 72 months |
| Challenged credit (500 to 599) | 10% to 20% cash down or trade equity | 36 to 60 months with specialized subprime lenders |
| Discharged bankruptcy or consumer proposal | 10% to 25% down payment | 24 to 48 months with verified income proof |
| Limited credit history or first-time borrower | 5% to 15% cash down or co-signer | 36 to 60 months depending on your monthly debt load |
Live inventory
ATVs on the lot right now
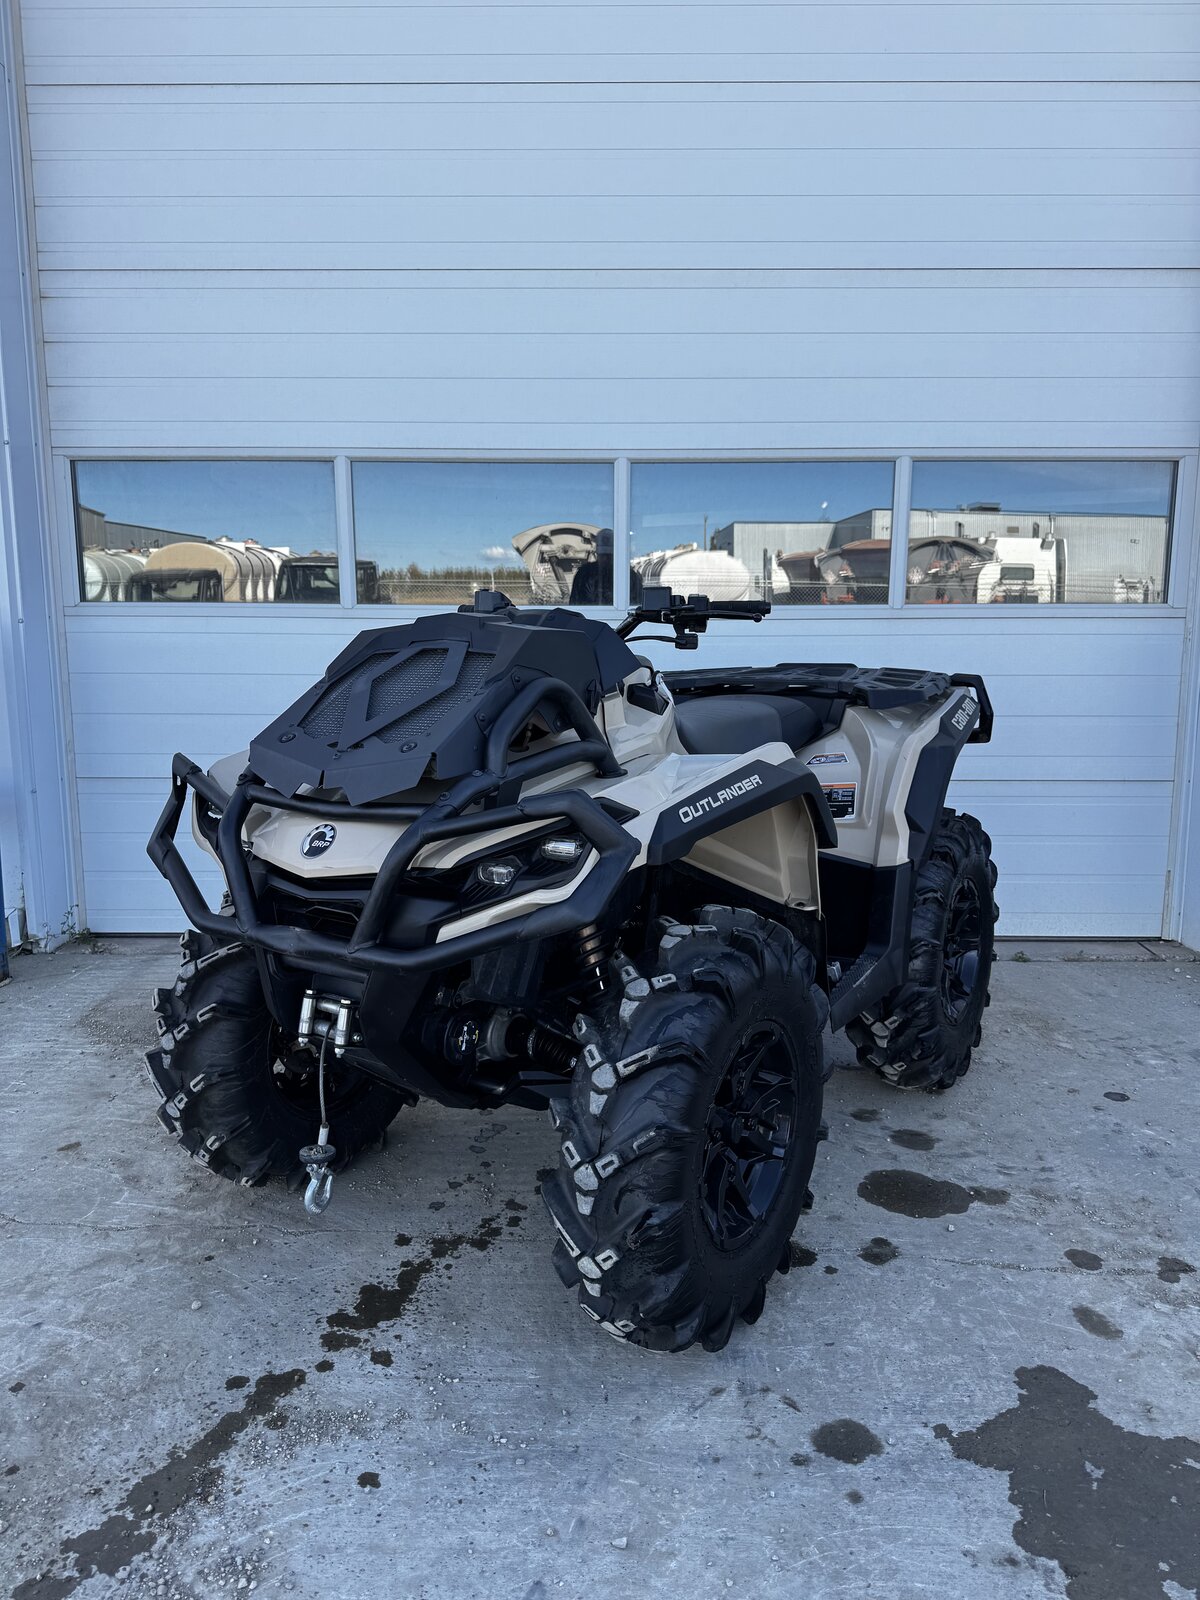
Live RMC inventory pulled directly from the dealership feed. Stock updates as units arrive and sell, so verify current availability before planning your visit.
Take the next step
Put this guide to work by comparing inventory or reviewing your financing options.
Straight answers
Frequently asked questions
What is the minimum credit score for an ATV loan?
There is no universal minimum credit score. Specialty lenders evaluate your complete profile, including income stability, employment history, and down payment, rather than rejecting an application based on a single number. Approval is conditional and never guaranteed.
Can I get ATV financing after a bankruptcy or consumer proposal?
Yes, many lenders consider applications from borrowers with a discharged bankruptcy or completed consumer proposal. You will need to provide your official discharge certificate and proof of steady, verifiable income.
Do I need a down payment to finance an ATV with bad credit?
A down payment is often required for subprime loans because it reduces lender risk and lowers the total amount financed. How much a lender wants down depends on your credit situation, the unit price, and the size of the loan. Cash down strengthens your file, but approval and terms always depend on each lender's own rules.
Does applying for ATV financing hurt my credit score?
Talking through your options with the finance desk does not always mean a full credit application is filed right away. When you authorize a formal credit application to lenders, that request can show on your credit bureau report. Ask the desk which step you are on before you submit.
Is there really no-credit-check ATV financing in Canada?
No legitimate powersports lender offers zero-credit-check financing at standard rates. Any program advertising guaranteed approval without a credit review usually charges extreme interest rates or hidden fees. Real lenders always review your credit and income.
Useful links
Plan your next step
Keep reading
Related resources
financing
ATV Financing in Alberta: How the Payment Path Works
How ATV financing really works at a dealership desk in Alberta, what documents to bring, how used units affect approval, and honest credit talk.
financing
ATV Financing Alberta: Edmonton and Leduc Desk Path
Looking at ATV financing in Alberta? See how an Edmonton or Leduc desk reviews a file, what to bring, used-unit notes, and how to move to live inventory.
financing
ATV Loan Canada: What Buyers Should Sort Before They Buy
Looking at an ATV loan in Canada? See how the desk reads the file, what docs matter, and how Ride Motor Company starts a real payment check.
financing
Camper Financing in Canada: How the Loan Works
See how camper financing works in Canada. Know what lenders review on the unit, how your tow vehicle fits, and what documents to prepare before you apply.