Financing a used Ski-Doo lets you spread the cost of a trail, mountain, or crossover sled over time, if approved. Whether you want an MXZ for groomed trail runs, a Summit for deep powder in the mountains, or a Renegade for mixed riding, match the total loan cost to your household budget before settling on a monthly payment.
Ride Motor Company works with powersports riders across Alberta and Canada, with physical dealership locations and service bays in Edmonton and Leduc. Knowing how lenders evaluate pre-owned snowmobiles and preparing your paperwork ahead of time keeps your finance conversation direct, clear, and focused on an affordable loan.
Start with the used Ski-Doo you want to finance
Financing depends on both your financial profile and the specific sled you select. Powersports borrowing typically uses a secured loan, where the vehicle acts as collateral. Because the snowmobile secures the borrowing, lenders evaluate the machine itself alongside your income and credit history.
When you shortlist a used sled, gather these details before discussing payment terms:
- Sled segment: Clarify whether the unit is a short-track trail model, a deep-snow mountain sled, or a utility-crossover machine.
- Year, hours, and distance: Note the model year, engine hours, and odometer reading; unit eligibility, rates, and terms depend on the lender, borrower, and exact machine.
- Condition and accessories: Check track condition, suspension wear, and add-ons like tunnel bags, heavy-duty bumpers, or aftermarket skis; ask how the lender values the sled and whether accessories affect valuation.
- Asking price: Know the cash price before sales taxes, registration fees, and lender charges to calculate realistic borrowing amounts.
You can browse live inventory to view available pre-owned snowmobiles across our Edmonton and Leduc showrooms. Having a specific unit or stock number ready allows the finance team to pull exact vehicle details for lender review.
Compare the full loan cost before the payment
Looking only at a low monthly or bi-weekly payment can hide the true cost of borrowing. Before signing any agreement, look closely at the amount financed, the total you borrow including financed charges. Check how the purchase price, down payment, documentation fees, and optional products combine to create that balance.
Ask the finance desk to explain each of these loan details:
- Cash price and down payment: Putting money down reduces your borrowing amount, but it does not prevent normal machine depreciation; leave room in your budget for seasonal maintenance and gear.
- Interest rate and repayment schedule: Review the annual interest rate and the amortization, the timeframe to pay off the loan. A longer repayment schedule lowers the regular payment amount but increases the total interest you pay over time.
- Total repayable amount: Review the total sum of all scheduled loan payments, then add your upfront cash to calculate the complete cost of buying the sled.
- Optional protections and warranties: Inspect optional mechanical coverage or debt protection line by line so you only pay for coverage you want.
- Early repayment rules: Ask whether making extra payments or clearing the loan early carries penalties or fees, and ensure those terms are written into the contract.
Buyers often ask about factory promotional rates seen in seasonal manufacturer advertisements. Review the current Canadian offer terms for the exact machine, model year, condition, and seller, alongside borrower criteria. Ask whether pre-owned snowmobiles qualify before adding an advertised promotional rate to your buying plan. Comparing total purchase costs rather than payment numbers ensures you choose the right financial path.
Documents to bring for a used Ski-Doo financing enquiry
Organizing your buyer paperwork early helps avoid delays during the approval review. Ask the finance team what documentation the lender requires to verify your identity, employment, and residence. For a wider explanation of powersports credit processes, you can review how snowmobile financing works.
These examples represent standard requirements; always confirm the exact records, dates, and formats your lender expects:
- Government photo ID: Check which identity documents the lender accepts, such as a valid driver licence or passport.
- Proof of regular income: Recent pay stubs, bank statements, or tax notices may be requested; let the desk know if your earnings are seasonal or self-employed so they can request suitable records.
- Banking information: Ask whether a void cheque or account confirmation form is needed for payment setup.
- Proof of address: A recent utility bill, lease, or statement may be required to verify your home address.
Include your monthly housing costs, existing loan payments, and the snowmobile's listing details in your file. Having these records ready lets the finance manager submit your request without back-and-forth requests.
What changes when your credit needs work
You can request financing even if your credit profile has past challenges. Lenders review your overall financial picture, including steady income, monthly debt obligations, credit history, and the value of the sled. Every application is reviewed on its own merits, and terms depend on the final assessment.
A lender may review your credit report, a record of your borrowing and repayment, to understand past payment performance. Scoring methods and credit checks differ across financial institutions; ask what check is required and how it is conducted before submitting your file. Specialist lenders may work with past credit setbacks or limited credit files, though their review can still lead to a declined application.
To build a stronger financing request:
- Pick a realistic sled: Choose a dependable sled with a price that leaves comfortable breathing room in your monthly budget.
- Put cash down: Providing an upfront payment lowers the loan-to-value, the loan balance compared to sled value, which reduces the lender's exposure.
- Declare existing debts: If you are trading in a machine that has an existing lien, a legal debt claim on the vehicle, confirm the payout figure and how any remaining balance will be handled.
- Document consistent income: Show reliable earnings over time, especially if your income involves seasonal work or contract projects.
Riding seasons and timing a snowmobile purchase
Pre-owned snowmobile prices and availability shift throughout the year across Western Canada. Selection is often widest in early autumn as riders prepare for the winter season, while late spring can bring different pricing as dealers clear inventory. Focus on inspecting and financing a verified machine with a clear service history rather than rushing into an uninspected listing.
Your next step with Ride Motor Company
Purchasing a pre-owned Ski-Doo begins with selecting the right sled and matching a financing package to your budget. Our finance team can explain the lender review process and outline the exact details required for your chosen machine.
When you are ready to review your financing options, you can start a financing conversation online. You can also confirm the unit location with our team to verify whether your selected sled is located at our Edmonton or Leduc showroom before you travel. We will review the numbers plainly, address your questions, and guide you through each step of the purchase.
| Loan component | Question to ask the desk | Why it changes your decision |
|---|---|---|
| Unit cash price | What is the total price before taxes and financing charges? | Sets the baseline for comparing the purchase price. |
| Down payment | How much cash or trade equity goes down upfront? | Reduces borrowing; payment also depends on rate and term. |
| Amount financed | What is the exact balance being financed after fees? | Shows how much you are borrowing, including financed fees. |
| Interest rate | Is the rate fixed for the entire loan term? | Affects interest costs alongside the balance and term. |
| Repayment term | How many months does the loan run? | Spreads payments out while affecting total interest paid. |
| Total repayable | What is the sum of every payment across the full term? | Shows scheduled loan repayments; add any upfront costs separately. |
| Lender and admin fees | Are document or loan registration fees included in the total? | Avoids unexpected cost surprises on the final contract. |
| Optional protections | What warranty or protection options are on the quote? | Lets you decide which optional items fit your budget. |
| Early payoff terms | Can the loan be paid off early without penalties? | Identifies any contract limits or costs for paying early. |
| Document type | Common examples; confirm lender requirements | Purpose for the lender |
|---|---|---|
| Personal identification | Government photo ID in a form the lender accepts | Verifies your legal identity and age. |
| Proof of income | Pay stubs, tax assessments, or bank statements as requested | Confirms steady earnings to support payments. |
| Banking information | Void cheque or bank form if required for payment setup | Supports payment setup after terms are agreed. |
| Proof of residence | Utility bill, lease, or bank statement if accepted | Confirms your physical address in your home province. |
| Sled information | Stock number, model year, hours, and serial number | Connects the loan agreement to a specific vehicle. |
Live inventory
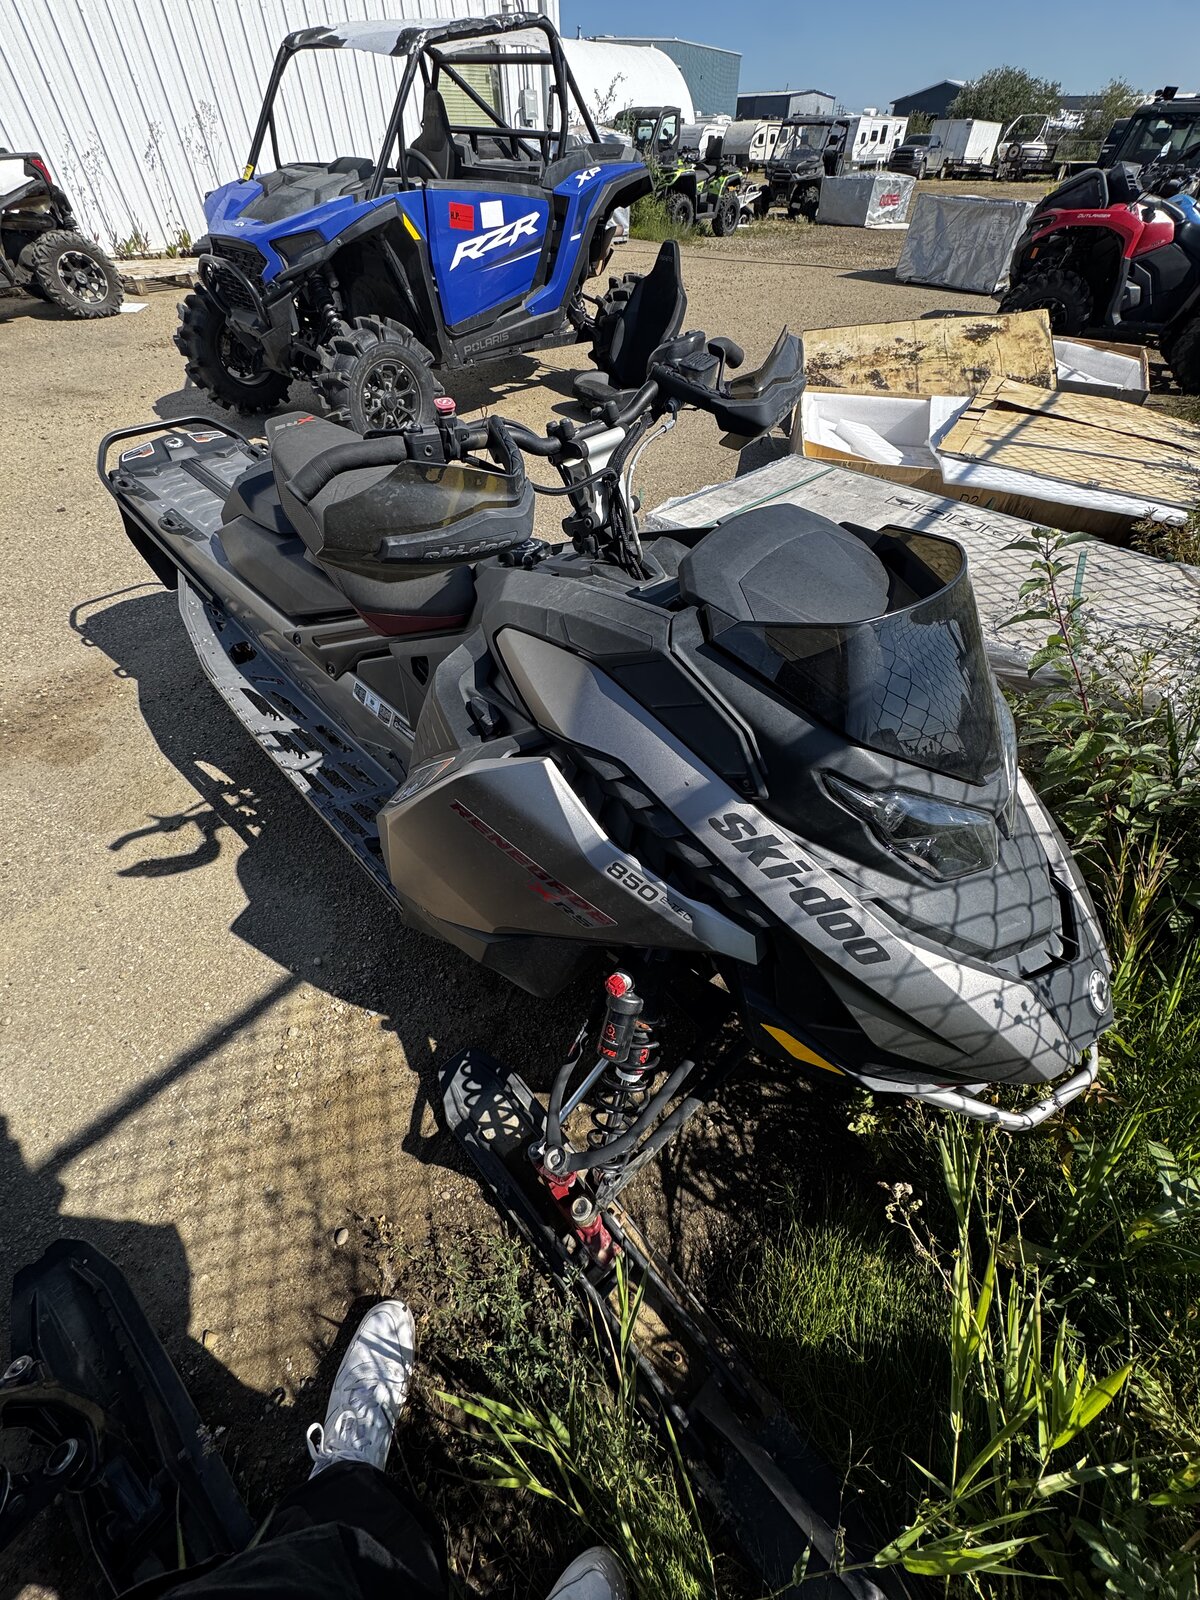
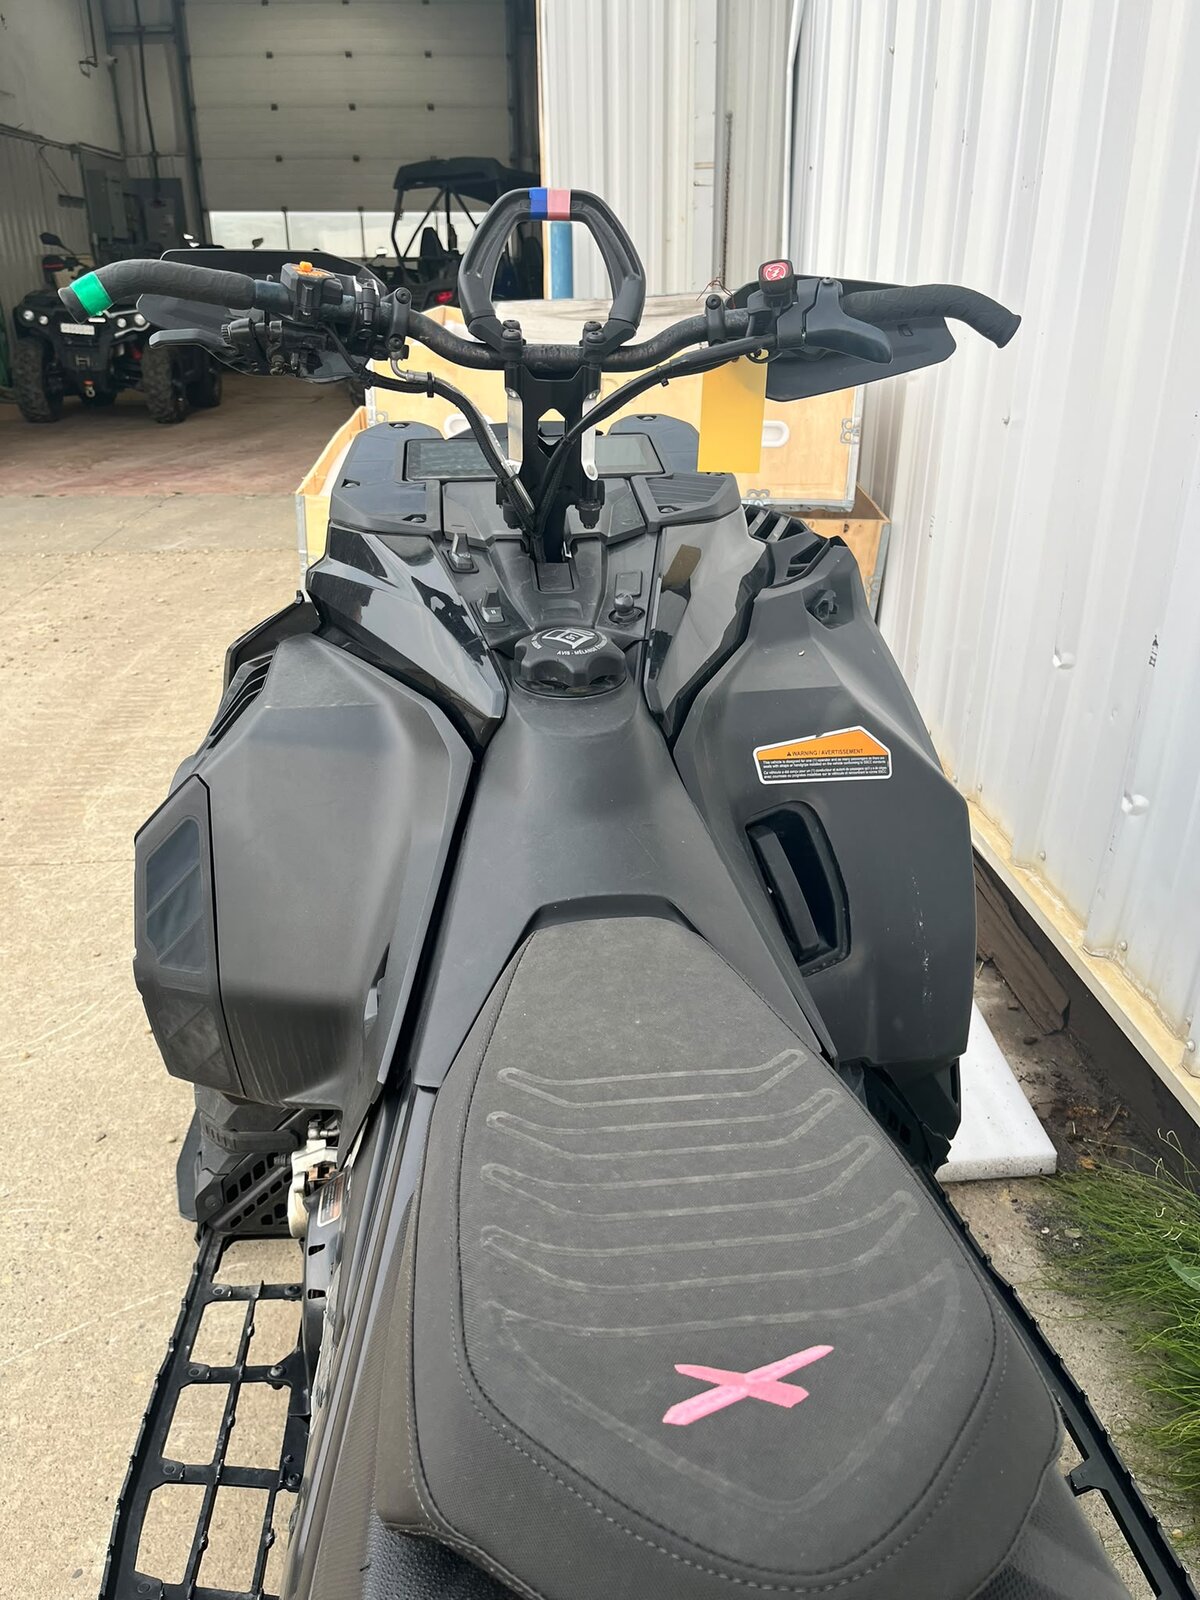
Snowmobiles on the lot right now
Live RMC inventory pulled from the dealership feed. Confirm the current list rather than trusting any count in an article.
Take the next step
Put this guide to work by comparing inventory or reviewing your financing options.
Straight answers
Frequently asked questions
Can I finance a used Ski-Doo in Canada?
Financing may be available; eligibility depends on the lender, borrower, and exact sled. Ask the finance team to confirm whether the sled's year, condition, and value meet lender requirements.
Does a Ski-Doo promotion apply to a used sled?
Check current Canadian offer terms for the exact machine, model year, condition, and seller. Ask whether a used unit qualifies and what borrower rules apply before factoring a promotion into your budget.
Can I apply if my credit needs work?
You can ask for a review even if your credit needs work. A lender still assesses income stability, debts, credit history, and sled details. A down payment or different sled may adjust the request, but neither guarantees approval.
What should I bring before asking about payments?
Gather identification, income evidence, monthly budget details, and the sled's listing or stock information. Ask the finance team which documents the lender accepts and whether address or banking records are needed upfront.
Useful links
Plan your next step
Keep reading